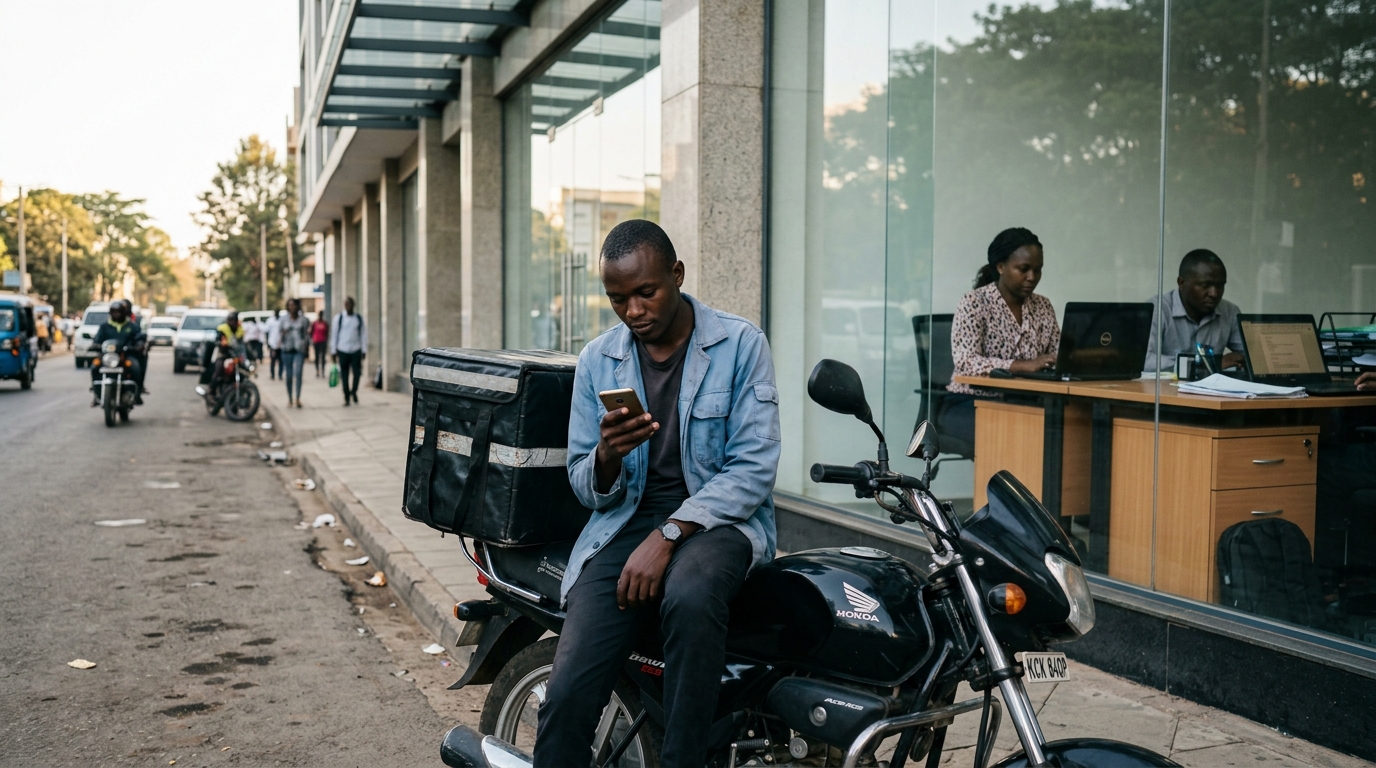
Kenya has roughly 3.3 million people in formal wage employment and 18.1 million working informally — a ratio the Kenya National Bureau of Statistics put at 83.8 per cent informal in its 2026 Economic Survey. Those 18.1 million people are not idle. They drive, deliver, code, clean, repair, sell and consult. What almost none of them have is a payslip.
This piece looks at the fastest-growing slice of that off-payroll workforce — platform and gig work — and at the question it forces on every Kenyan business that has ever paid someone as a "consultant" or "freelancer" instead of putting them on payroll. The legal line between the two is not drawn by the label on the contract, and the cost of getting it wrong lands on the employer, not the worker.
Key takeaways
- Informal work accounts for 83.8 per cent of Kenyan employment — 18.1 million people against 3.3 million formal wage jobs, according to KNBS data for 2025.
- Ipsos Strategy3 sizes Kenya's gig economy at about $1.03 billion and 1.55 million workers, with e-commerce and ride-hailing the two biggest segments.
- Kenyan courts decide employment status on substance, not on the words "consultant" or "contract for service" — control, integration, economic reality and mutuality of obligation all weigh in.
- A long-running "consultant" found to have been an employee can trigger PAYE arrears, statutory deductions and service pay of 15 days' wages for every completed year under section 35(5) of the Employment Act.
How big is Kenya's gig economy?
Bigger than most payroll managers assume. Ipsos Strategy3's multi-country gig economy study, published early in 2026, valued Kenya's platform-work economy at roughly $1.03 billion and estimated about 1.55 million people earning from it. Business Daily has used a similar figure — around 1.5 million Kenyans whose livelihoods run through digital platforms.
The composition is the surprising part. Ride-hailing gets the headlines and the protests, but it is not the largest segment. In the Ipsos breakdown, e-commerce accounts for about 42 per cent of activity, ride-hailing 20 per cent, freelancing 17 per cent, micro-tasks 10 per cent and remote work 9 per cent. The typical Kenyan gig worker is closer to a vendor moving goods through a marketplace than to a driver waiting for a ping.
Nor is this reliably a side hustle. Among ride-hailing drivers surveyed, 53 per cent said platform earnings were their primary source of income. For roughly a fifth of them, the platform accounted for more than three quarters of total household income. That is not supplementary earning. That is a job, without any of a job's statutory architecture.
Why 18 million Kenyans work without a payslip
The formal sector is growing, just slowly. KNBS recorded formal employment rising to about 3.3 million in 2025, while informal employment climbed to 18.1 million from 17.4 million the year before. In absolute terms, the informal economy absorbed the overwhelming majority of the year's new work.
That matters beyond statistics. Kenya's entire statutory machinery — PAYE, NSSF, SHIF, the Affordable Housing Levy, leave entitlements, notice periods — is bolted onto the employment relationship. No employment relationship, no deductions, no coverage. A platform worker who crashes a motorbike has no sick-leave entitlement to fall back on and, unless they registered voluntarily, no statutory social security either.
Is a gig worker an employee under Kenyan law?
Sometimes. The Employment Act 2007 defines a contract of service in section 2 as an agreement to employ — written or oral, express or implied. The word "implied" is doing a great deal of work in that sentence, because it means a court can find an employment relationship that neither party wrote down.
Kenyan courts have long applied a cluster of tests rather than a single rule: the control test, which asks how much the payer directs the way the work is done; the integration test, which asks whether the worker is part of the organisation or merely serves it; the economic reality test, which asks whether the worker genuinely bears entrepreneurial risk; and mutuality of obligation. Decisions such as Maurice Oduor Okech v Chequered Flag Limited and Fredrick Byakika v Mutiso Menezes International make the same underlying point — the terminology the parties chose does not settle the question.
Platform work sits awkwardly across those tests. A driver sets their own hours, which points away from employment. But the algorithm sets the price, the route, the acceptance rate and the grounds for deactivation, which points firmly back toward control. No Kenyan statute yet resolves the tension. Policy discussion has turned to international labour standards, and the Kenya Union of Gig Workers has pushed for reclassification, but as of now there is no settled statutory category for platform workers. Anyone who tells you the question is closed is guessing.
What you must withhold when you pay a freelancer in Kenya
If the engagement really is a contract for services, the tax treatment is withholding tax rather than PAYE. KRA's published rates put withholding tax on management, professional and consultancy fees paid to residents at 5 per cent, rising to 20 per cent for non-residents, with a 15 per cent rate for consultancy fees paid to East African Community citizens. Section 35 of the Income Tax Act requires the deduction to be remitted within five working days.
Two things trip up small finance teams here. The first is treating withholding tax as the contractor's problem — it is not; the obligation to deduct and remit sits with the payer. The second is assuming that because withholding tax was deducted correctly, the classification must have been correct too. KRA and the Employment and Labour Relations Court answer different questions, and a clean withholding tax record is no defence against a finding that the person was an employee all along.
The mistake most businesses make, and what it costs
The expensive error is the permanent consultant: someone engaged on a "contract for services" who has worked the same hours, under the same supervisor, from the same desk, for three or four years. It is usually done for cash-flow reasons and it feels harmless, because the worker agreed to it.
Then the relationship ends badly. If the court finds a contract of service, the arithmetic reverses at once. Annual leave accrues at the statutory minimum of 21 working days a year and is payable on termination. Notice applies. Unremitted PAYE and statutory deductions become recoverable with the penalties and interest attaching to late remittance. And section 35(5) of the Employment Act provides service pay of 15 days' wages for every completed year — the clause that turns a four-year "consultancy" into a two-month payout.
There is a quiet irony in section 35(6). The service-pay obligation falls away where the employee is a member of NSSF or a registered pension or gratuity scheme. The employer who dodged enrolling the consultant in NSSF to save a few hundred shillings a month is precisely the employer who cannot rely on that exemption.
How to hire flexibly without creating a hidden employee
Flexible hiring is legitimate and often sensible. The discipline is making the substance match the paperwork. Define deliverables rather than working hours. Let the contractor decide how and when the work gets done, and resist the urge to slot them into the daily stand-up. Keep the scope finite. Expect them to invoice, carry their own tools and work for other clients.
Where none of that is realistic — where you need someone on site, on your schedule, under your direction, indefinitely — the honest answer is that you need an employee. Put them on payroll, run the statutory deductions, and price the role accordingly. The alternative arrives with interest.
Frequently asked questions
Can a contract say "this is not employment" and make it true?
No. A clause disclaiming employment is evidence of what the parties intended, and nothing more. Kenyan courts examine how the relationship actually operated — supervision, integration, exclusivity, who bore the risk — and a disclaimer that contradicts the facts on the ground carries very little weight.
Do I have to deduct NSSF and SHIF for a genuine freelancer?
Not as their employer, because statutory employee deductions attach to a contract of service. A genuine independent contractor is responsible for their own contributions, including voluntary NSSF membership. The risk is not the freelancer's status on paper but whether you can defend that status if it is tested — which is far easier when your payroll system holds clean, dated records for everyone you pay, with a system like Force HRM keeping contractor and employee records distinct.
Is Kenya about to regulate platform work?
There is pressure in that direction from unions, courts and policymakers, and discussion of adopting international labour standards, but no Kenyan statute currently creates a distinct legal category for platform workers. Treat it as a live question through 2027, and structure engagements so a reclassification would not be catastrophic.
Getting the classification right before someone else does
The off-payroll workforce is not a fringe case in Kenya; by the numbers it is the mainstream, and the compliance question it raises is simply which of your people are actually employees. Force HRM is built for that decision: a mobile-first Kenyan payroll and HR platform that calculates PAYE, SHIF, NSSF and the Affordable Housing Levy correctly for the people who belong on payroll, keeps a defensible record for everyone you pay, and can be operated conversationally through AI assistants over MCP. If you are reviewing how your contractors and employees are classified this quarter, see how Force HRM handles Kenyan payroll compliance.